

Behind it sits a 20 to 25-year engine fleet being ordered into a compute market whose hardware is depreciated over six.
Related reading: Nvidia is starting to insure the residual-value problem Michael Burry identified, Crusoe lost, and ERCOT curtailment is now sized to the meter, not the generator, and the residual value put Nvidia hasn’t priced.
Nvidia put up to US$105 billion behind an AI data center campus this month. Read the guaranty, and it names three project agreements that exist only because Nvidia signed: a 20-year lease, a retail electricity contract and a transmission upgrade agreement.
It does not name the plant producing the electricity.
That omission matters because developers are simultaneously ordering 20 to 25 year generating equipment to accelerate data centers whose compute economics turn over on a two to six year hardware clock.
Joule Capital Partners is an unusually clean example. 636 Caterpillar G3520K gensets are slotted for phase one of a 4,000-acre campus in Millard County, Utah, roughly 1.5 GW ramping by early 2028, on a dedicated gas lateral that trade reporting attributes to Kern River Gas Transmission. I haven’t been able to tie that lateral to a specific Kern River filing, so treat the pipeline name as reported rather than confirmed. On a proper overhaul program, that fleet is a 20 to 25 year asset, which is an estimate rather than a disclosed figure. The lateral and the county entitlement don’t have a life at all; they’re site-permanent. The revenue that pays for all of it comes from compute contracts priced off hardware that CoreWeave carries on a six-year straight-line schedule and that Michael Burry puts at 2.5 to 3.5 years of real economic life.
The credit market has spent nine months arguing about which of those two numbers is right. That argument sits above the power layer and never reaches it.
Nvidia’s Q2 FY2027 filings on 26 August disclose three separate infrastructure-support buckets whose headline maximum amounts total US$114.8 billion. They are not economically additive exposures: US$105 billion of phased and declining PORTS-Pike residual value guarantees, US$6.3 billion of CoreWeave capacity-purchase obligations and US$3.5 billion of maximum gross exposure on what the CFO commentary calls land, power and shell guarantees for AI cloud partners’ lease obligations. Alongside those sits the financing-platform residual support, which the quarter deliberately left undefined.
Count the instruments and read what each one names, because Nvidia has now named the power layer itself.
The Ohio structure repays a close read, because it’s the clearest statement yet of what Nvidia is willing to insure. SB Energy builds, owns and operates the PORTS-Pike campus in Piketon, Ohio, which will exclusively host Nvidia infrastructure under 20-year leases to OpenAI. NVIDIA signed multiple residual value guarantees covering roughly 4.25 GW of IT load, with sole discretion to extend credit support to about 3.8 GW more, capped cumulatively at US$105 billion, down from the roughly US$250 billion discussed in late July. The guarantees become effective in phases as data centers reach ready-for-service, the first expected in fiscal 2029, and the exposure declines as OpenAI fulfills lease payments. If a guarantee triggers, Nvidia may assume the lease, push the landlord toward a replacement tenant, or initiate a sale. OpenAI has agreed to reimburse and indemnify, and Nvidia’s own risk factor says it may not recover promptly or in full.
Now read the recitals in the Form of Residual Value Guaranty filed as Exhibit 10.1 to the Q2 10-Q. A Power Affiliate enters power purchase and supply agreements to buy retail electricity for the premises. The same Power Affiliate commits to a GridCo to complete the transmission network upgrades needed to deliver that power. And the landlord and the Power Affiliate agreed to sign the lease, the PPA and the Transmission Agreement if and only if Nvidia executed the guaranty.
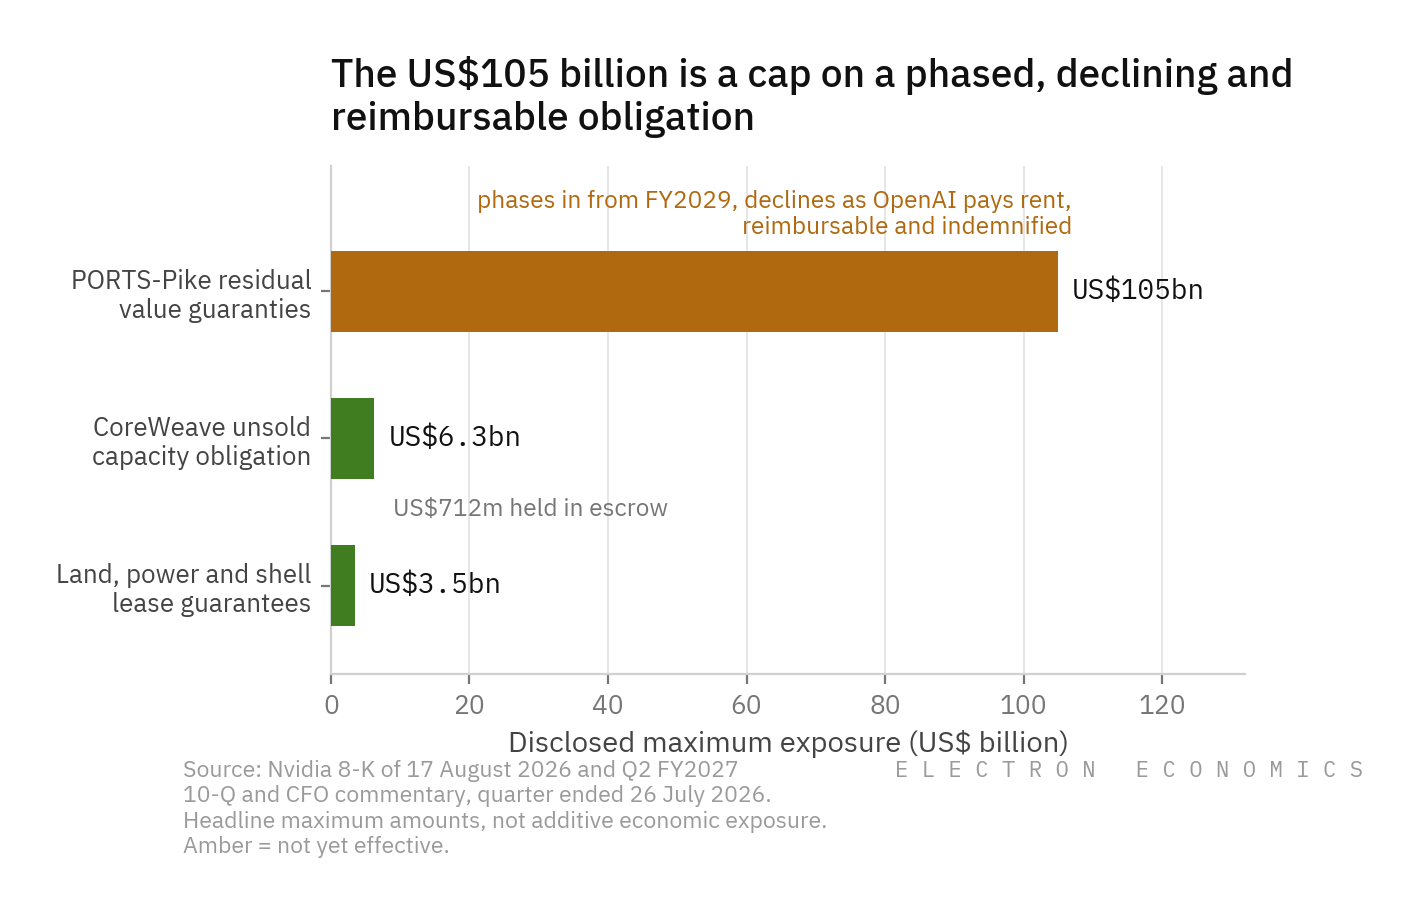
Fig 1 — Headline maximum amounts, not additive economic exposure and not cash at risk today. Sources in the figure.
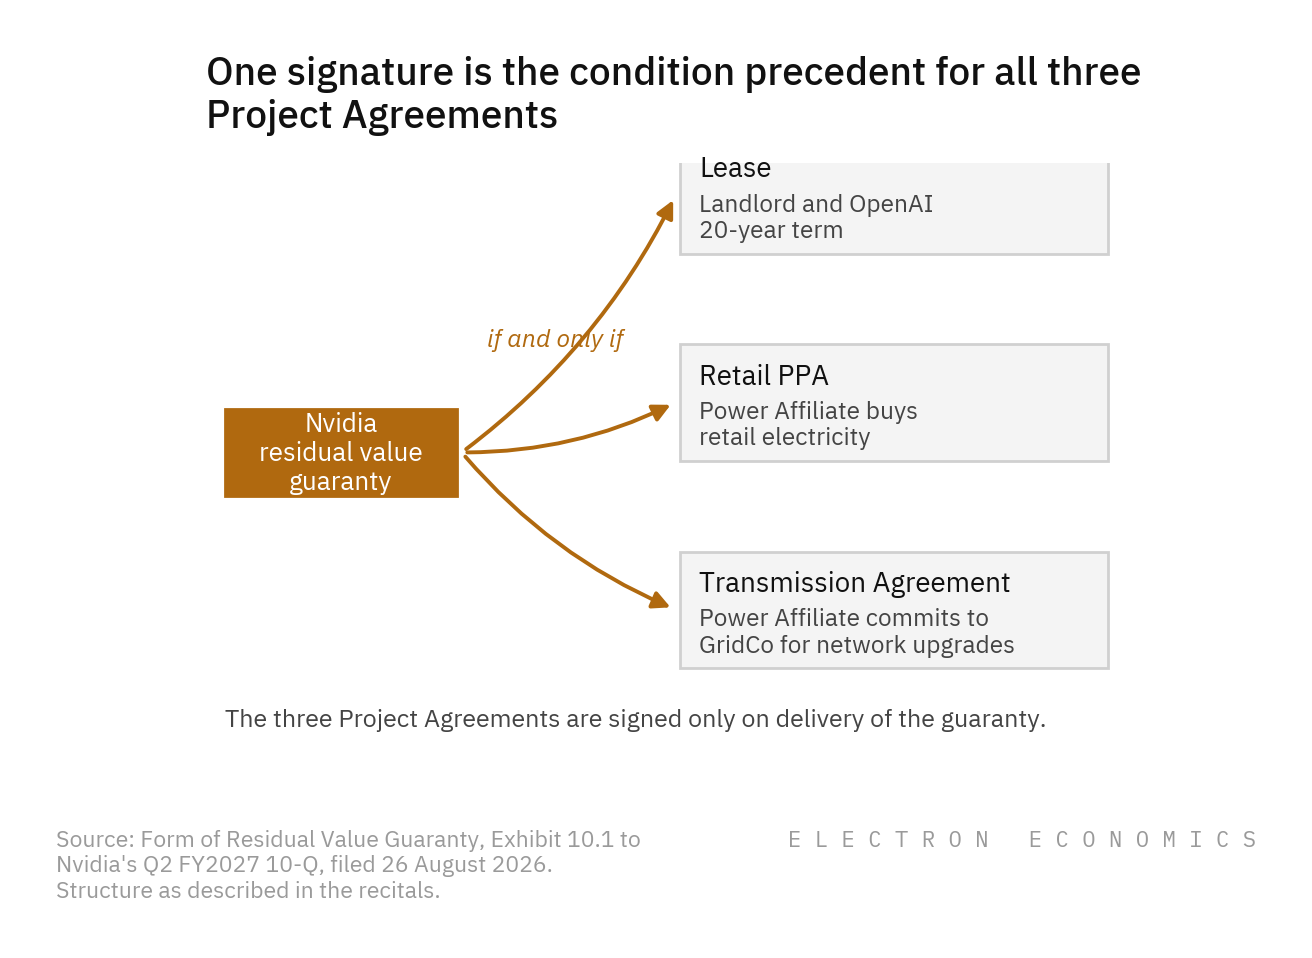
Fig 2 — The lease, the retail PPA and the transmission upgrade commitment are signed on delivery of the guaranty. Sources in the figure.
The largest residual guarantee ever written in this sector went to a campus supplied under a retail PPA with contracted network upgrades. Nvidia’s US$105 billion is the condition precedent for a utility procurement path. It is not a floor under anybody’s engines.
NVIDIA will now guarantee power. It guaranteed a retail power purchase agreement and a commitment to a transmission upgrade for a grid-connected campus. It did not guarantee anyone’s generating assets. Read the exhibit, and the difference is a matter of recitals rather than interpretation.
So the market is treating behind-the-meter gas as a speed-to-power problem, priced against equipment lead times. The lease arithmetic and the guaranty documents show something different: power is the largest single line in a compute occupancy cost, it carries by far the longest commitment in the stack, and when the best-informed balance sheet in the industry chose which version of it to stand behind, it chose the grid.
Everything under the GPU is committed for longer
Line up the durations, and the mismatch stops being an accounting debate.
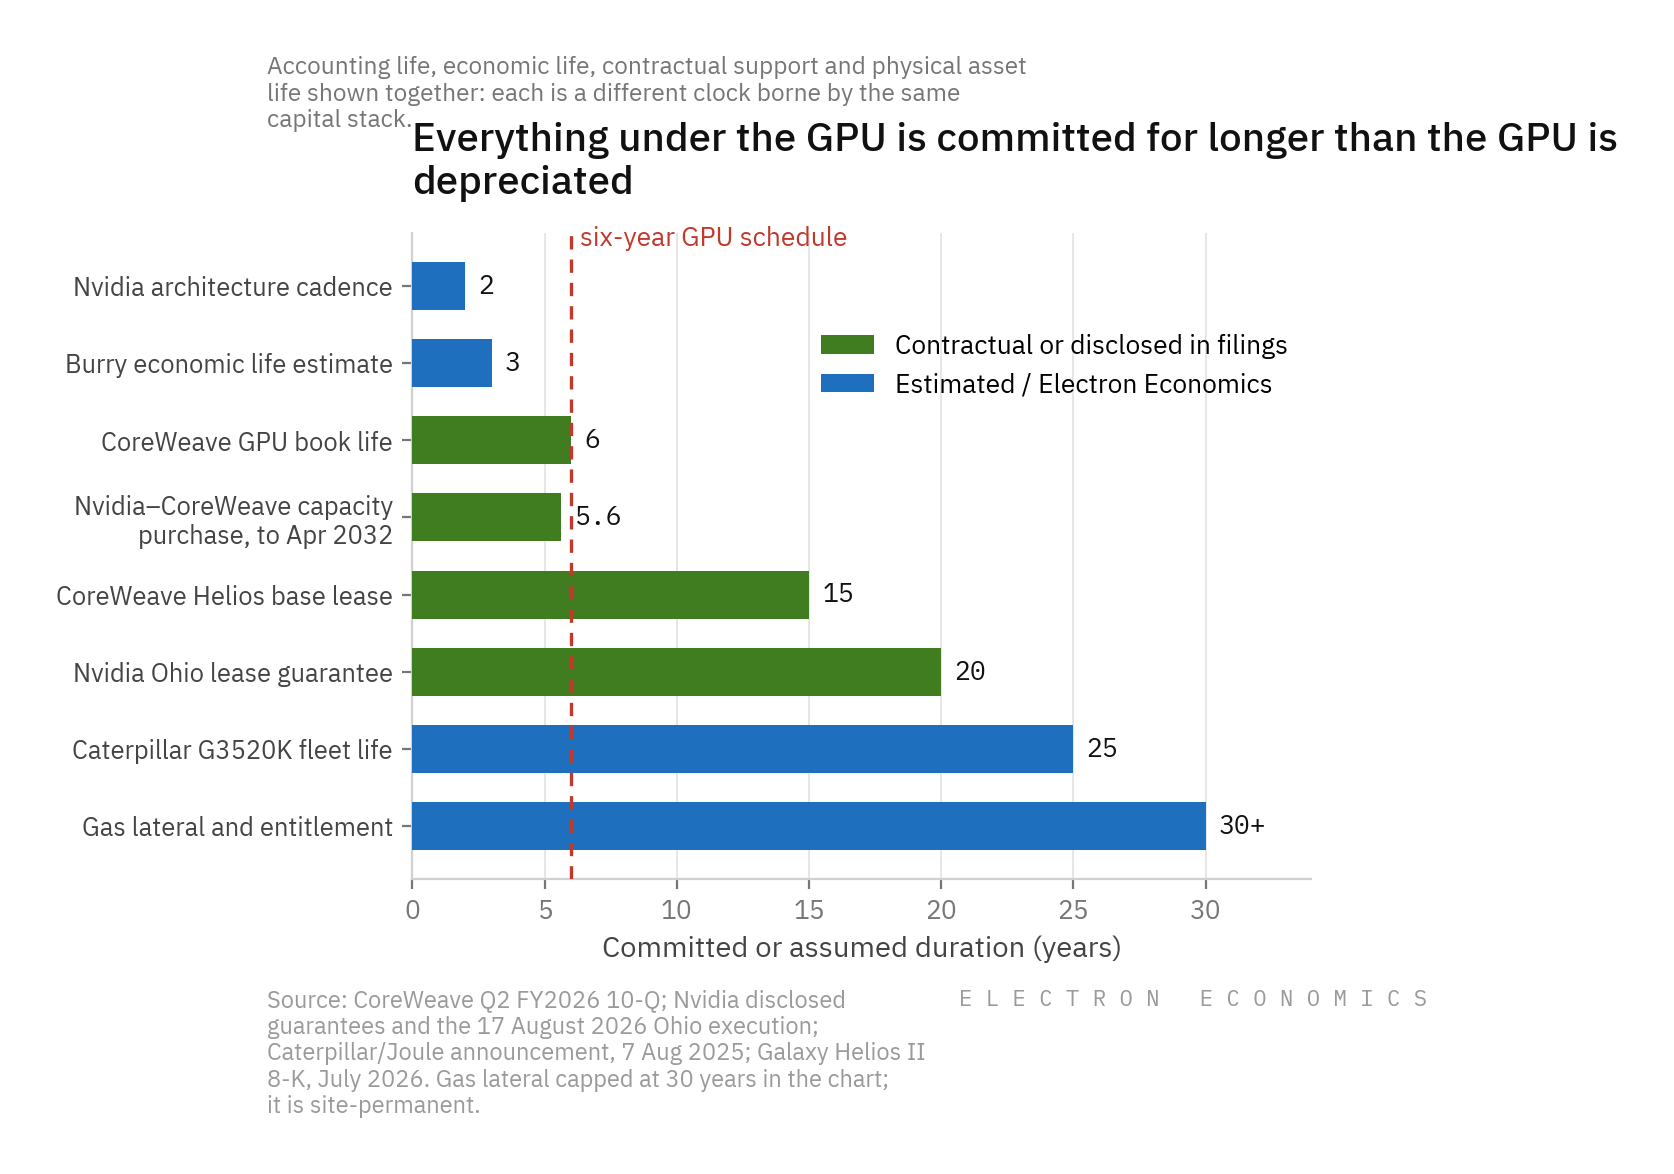
Fig 3 — Accounting life, economic life, contractual support and physical asset life are deliberately shown together. Each is a different clock borne by the same capital stack. Sources in the figure.
The quarter itself is the backdrop. Nvidia printed US$96.2 billion of revenue, up 106 percent, with US$89.0 billion of that from data center, and guided the current quarter to US$108.0 billion against a street looking for US$104.2 billion. Colette Kress put top-five hyperscaler capex at US$1.3 trillion next year against US$800 billion in 2026. Nobody reading this needs convincing that the demand is real. The question is which layer of the stack gets paid for carrying it.
Nvidia ships a new architecture roughly every two years. Burry’s refined estimate of real economic life is 2.5 to 3.5 years. CoreWeave books six, and held at six in the Q2 10-Q with no revision and no discussion on the call, against D&A that more than doubled year on year. Amazon walked the other way, cutting the life of a subset of servers and networking equipment from six years to five effective January 2025, and printed the effect: Q3 2025 depreciation up US$392 million, net income down US$298 million.
Below that line, nothing is short. A hyperscale lease runs 15 years initial term with extensions; CoreWeave’s Helios leases are 15-year base with two five-year options, a potential 25 years. The Ohio lease runs 20 years, with the first 800 MW expected in 2028 and roughly 8 GW at full build. The G3520K fleet runs 20 to 25 years on a proper overhaul program. The gas lateral, the county conditional use permit and the air authorization don’t expire in any commercially meaningful sense, and none of them is portable.
That last point is the one developers underweight. A genset can be trucked. A dedicated lateral to a single campus cannot.
Texas supplies another example of site-level duration risk. In Docket No. 59220 on 24 July 2026 the PUCT imposed curtailment conditions that attach to the physical assets, bind successors-in-interest and require reconsideration between 36 and 60 months. The decision governs a net-metered co-location behind an existing registered generator rather than a fully islanded facility, so don’t extrapolate it to Joule or to Nscale’s Monarch campus in West Virginia, which is built to run independently of the grid with a future interconnection preserved as an option. But it shows the shape of the problem: regulatory conditions can attach to a site on a much shorter review clock than the equipment life, and they travel to whoever buys it. I unpacked the order here.
The “islanded today, connected later” option, meanwhile, is still unpriced. ERCOT’s own position is that a facility with no grid connection generally falls outside its interconnection process, and Monarch sits in PJM, whose regime is not ERCOT’s. That option is set to 0 in many models.
The lease rate became the power price
Two disclosures this summer make the arithmetic possible without guessing.
Ionic Digital’s S-1 discloses a 126-month triple-net lease to Nscale over the full 234 MW at its Ward County site in Barstow, Texas, executed in October 2025, amended in February 2026, representing about US$1.95 billion of contracted revenue with monthly fixed payments starting August 2026. Divide it out and the rent is US$66 per kW per month. The tenant carries taxes, insurance, maintenance and the power contract.
Read Ward County as the floor. It’s a converted bitcoin mining site, land plus a powered building at the bottom of the ladder.
For the built product, Galaxy’s Helios II investor presentation, filed on Form 8-K in July 2026 behind the US$3.507 billion note offering, runs an illustrative 2028 model of US$472 million of rent and US$424 million of net operating income against 260 MW of critical IT load leased to CoreWeave. That’s US$151 per kW per month of rent, on a 15-year base term with two five-year extensions, a 13.7 percent starting gross yield on cost and a CPI-linked escalator of 3 to 5 percent. The same model implies about US$15 per kW per month of retained operating cost, which is what produces the 90 percent NOI margin. Galaxy describes the structure as near triple-net, with CoreWeave covering utilities, taxes, insurance, maintenance and ordinary repairs while Galaxy keeps certain mechanical, cooling, electrical and administrative personnel costs outside the white space.
Be careful what that US$15 is. It’s Galaxy’s underwriting assumption for its own retained Helios costs, not a generic data center opex benchmark and not something the tenant pays on top of rent. It’s useful here for a narrower reason: it tells you how little of a US$151 rent is operating cost, which means almost all of that number is capital recovery on a building. Directionally the operating company agrees with the model, since Galaxy delivered Phase I in Q2 2026 and guided to project-level adjusted EBITDA margins above 90 percent.
So the rent ladder runs from US$66 at the floor to US$151 for a purpose-built AI hall, both from filings rather than broker surveys. Now add the electrons, which the tenant pays separately for in both structures. One kW of critical IT load at an 85 percent load factor and a 1.2 PUE draws roughly 745 kWh a month, which is my assumption rather than a filed number and moves the answer by about 8 percent per 0.1 of PUE.
RaboResearch’s sustained cost of delivered energy, which escalates fuel and folds in the overhauls a gas fleet needs when it runs at high capacity factor, puts reciprocating engines at about US$107 per MWh at year five, aeroderivatives at US$106 and combined cycle at US$101, with behind-the-meter gas overall running US$100 to US$165 per MWh against US$90 to US$95 for grid-connected supply.
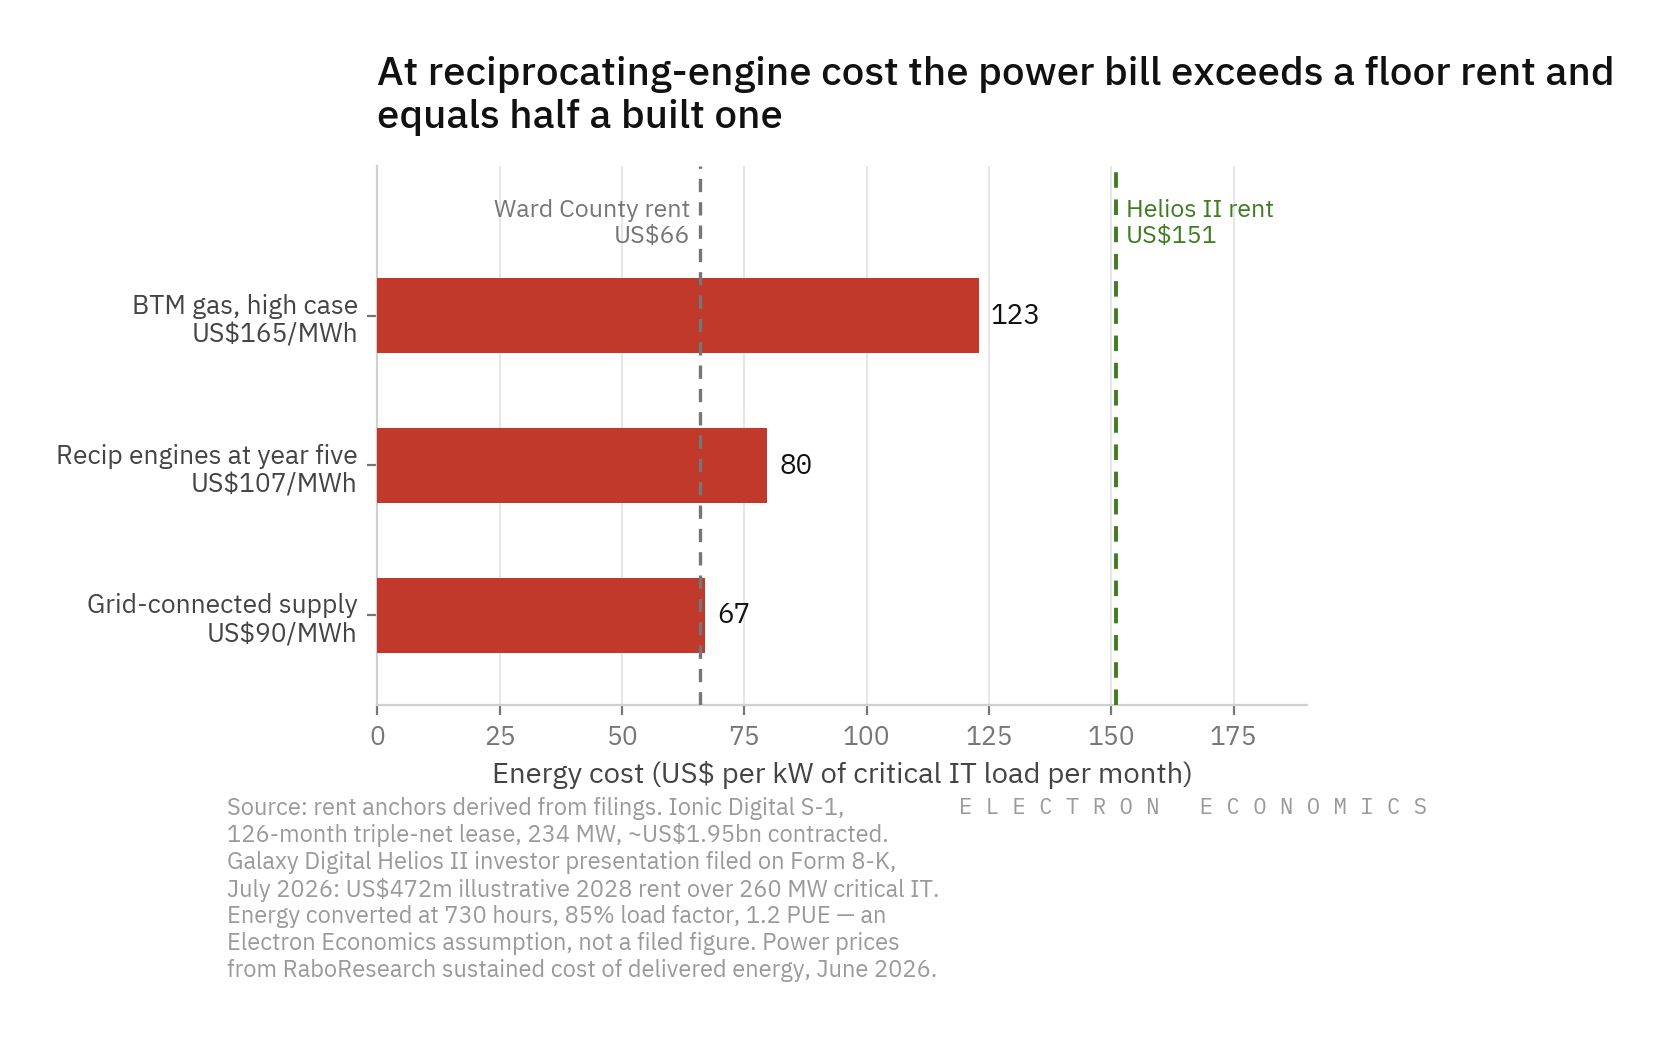
Fig 4 — At recip cost the energy line runs about US$80 per kW per month: 121 percent of the Ward County floor rent and 53 percent of Helios II’s contracted rent. Both rent anchors are derived from filings. Sources in the figure.
At US$107 per MWh, energy costs about US$80 per kW per month. That’s 121 percent of the Ward County rent and 53 percent of the Helios II rent. At the top of Rabobank’s range it’s US$123, which exceeds the floor rent by nearly double and covers 81 percent of the built one. So power is larger than the floor rent, and more than half the rent on a purpose-built AI hall.
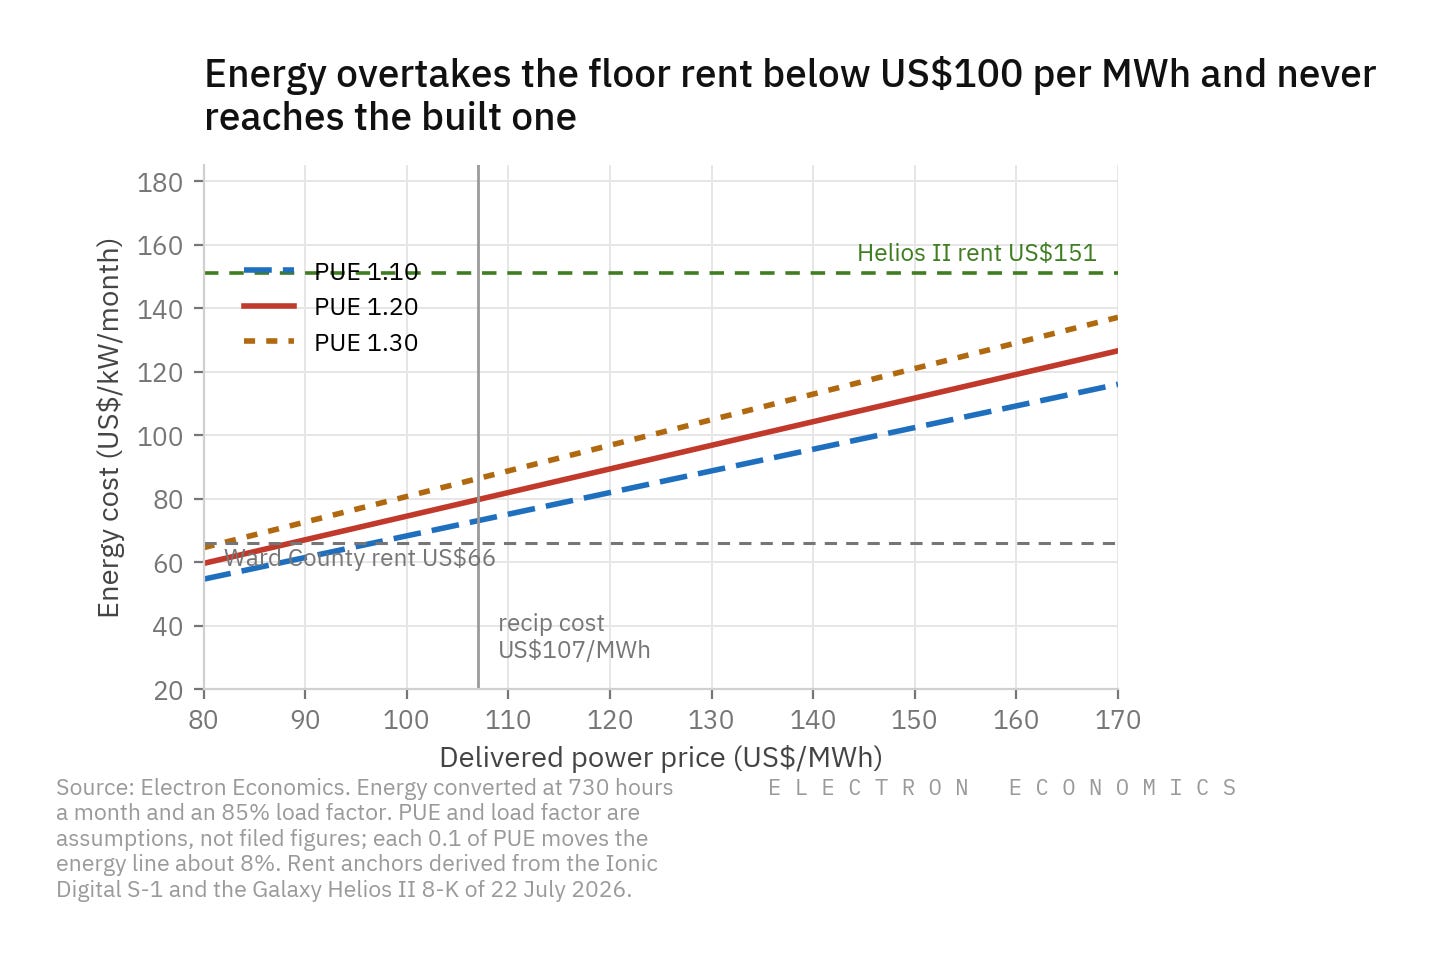
Fig 5 — The conversion rests on load factor and PUE, so here is the whole surface rather than one point estimate. Sources in the figure.
That comparison is the point. Galaxy’s own model says roughly 90 percent of Helios II rent is capital recovery rather than operating cost, and Galaxy has a US$3.5 billion note issue and a 15-year CoreWeave lease standing behind that capital. The power bill, which is the same order of magnitude, has a plant behind it that nobody has financed on a 15-year contracted basis and nobody has guaranteed.
Push that back through the chain. A compute lease is a claim on contract revenue. Contract revenue is priced against hardware whose carrying value depends on a useful-life assumption. So the power price a behind-the-meter developer can charge is a second derivative of a depreciation schedule, and it’s the largest number in the stack.
Where the residual protection stops
The instrument taxonomy matters commercially rather than pedantically. Financing support protects a borrower against cost of capital. A revenue or utilization floor protects against underutilization and sizes against a debt service coverage ratio. A residual-value guarantee protects an asset-backed lender against collateral depreciation and sizes against loan-to-value. They pay different parties, against different tests, at different times.
Sort Nvidia’s disclosed positions by which layer they attach to.
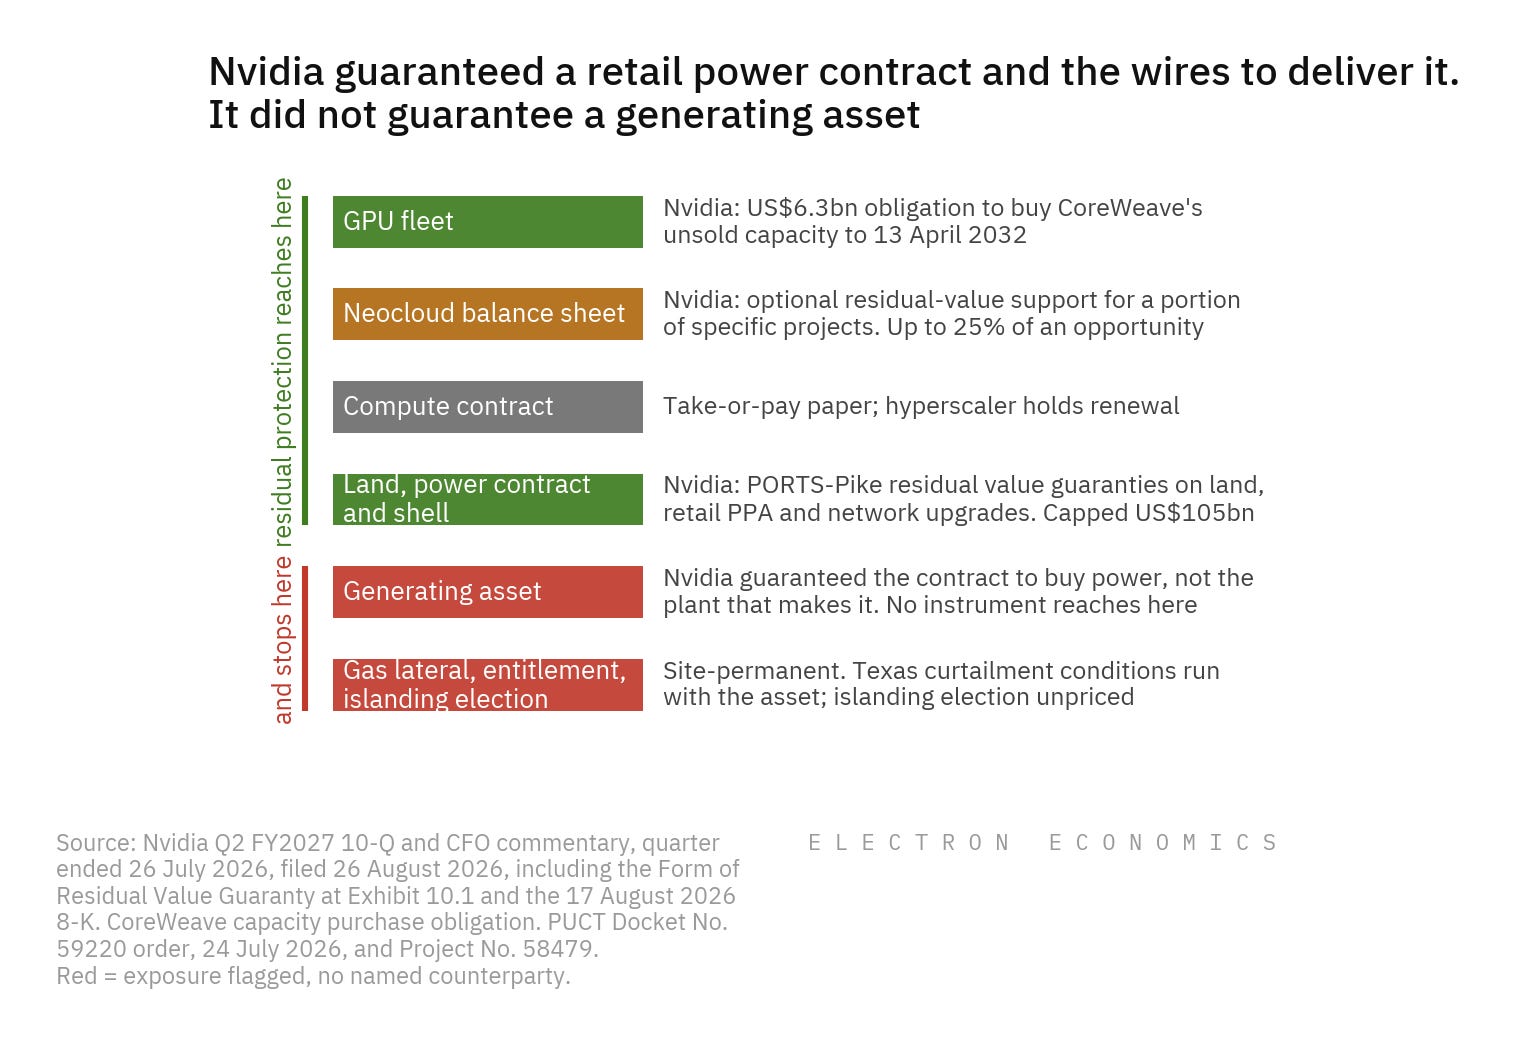
Fig 6 — Protection reaches the GPU fleet, the neocloud, the compute contract, and in Ohio the land, the retail power contract, the network upgrades and the shell. It stops before anyone’s generating asset. Sources in the figure.
The US$6.3 billion CoreWeave obligation buys unsold cloud capacity. The PORTS-Pike guaranties are residual value protection on land, power procurement and shell, capped, phased, declining and reimbursable. The US$3.5 billion of guarantees the CFO commentary describes as land, power and shell for AI cloud partners’ lease obligations carry a named maximum gross exposure and US$712 million held in escrow. The financing-platform support is the one worth reading twice, because the denominator does the work. On 11 August, describing the platforms with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR, Nvidia said it may provide a residual-value support mechanism for up to 25 percent of an opportunity, assessed project by project. That is support sized at up to a quarter of a financing opportunity. It is not a claim that a GPU is worth 25 percent of cost, or that Nvidia repurchases at that level, or that a lender recovers 25 percent of original capex. Then the 26 August 10-Q had the chance to turn that sentence into an accounting disclosure and went the other way: the platforms are independently underwritten by the capital providers, and at Nvidia’s option it may provide limited residual-value support for a portion of specific projects. No percentage, no definition of residual value, no methodology, and optional. Undisclosed is not the same thing as unlimited, and a marketing number is not the same thing as a filed one.
So the honest version of my earlier claim is narrower and more damning. Nvidia has guaranteed power. It guaranteed the contract to buy power and the contract to upgrade the wires. No disclosed instrument guarantees the residual value of a generating asset, which is the thing a behind-the-meter developer actually owns.
There’s a structural reason for that, and Nvidia stated it in the quarter. The company says it will focus on exceptional sites where visible, durable demand can support multiple generations of Nvidia compute. My read of that underwriting rule is straightforward: Nvidia is willing to stand behind infrastructure that can support multiple generations of compute, which is what land, a grid connection and a shell do. No disclosed instrument shows it making the same judgment about a bespoke merchant engine fleet. That’s an inference from disclosed behavior rather than something the filing states.
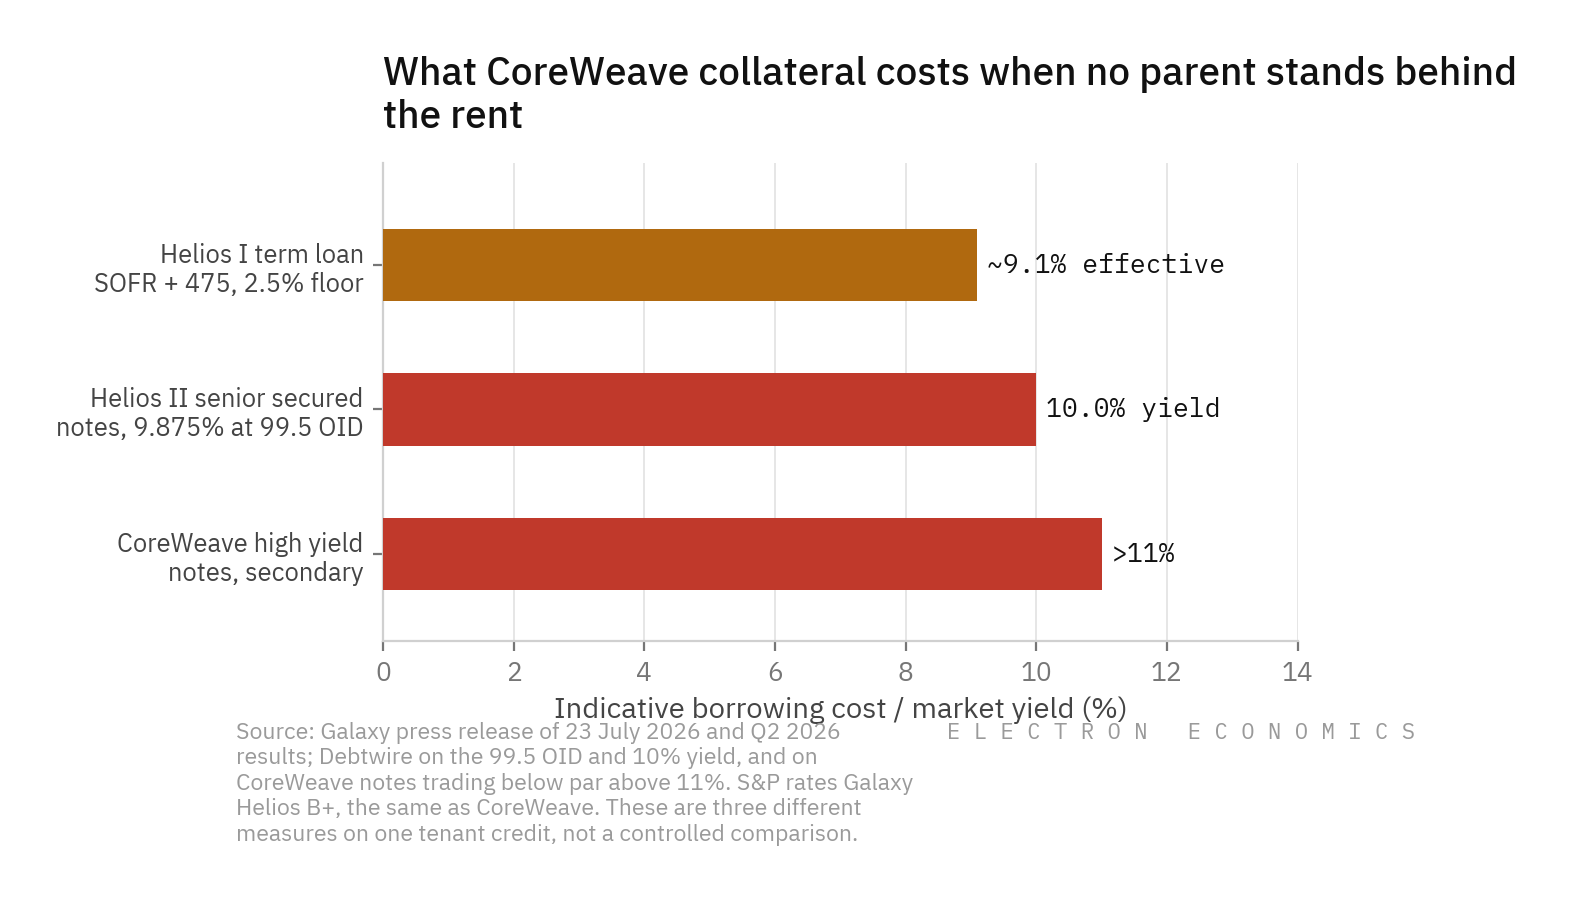
Fig 7 — Three different measures on one tenant credit, none carrying a parent rent guarantee. Not a controlled comparison. Sources in the figure.
The credit market has already priced what it thinks of unguaranteed exposure in this chain. Galaxy’s Helios II project bond, CoreWeave as tenant and only a completion guarantee from Galaxy Digital Holdings, cleared at 9.875 percent. Helios I was a US$1.4 billion term loan at SOFR plus 475 with a 2.5 percent floor, roughly 9.1 percent effective at 80 percent loan to cost. CoreWeave’s own high yield paper has traded below par above 11 percent. Those are three different measures on one tenant credit rather than a controlled comparison, so don’t read the spread between them as a clean number. The structural tell is elsewhere: Helios II amortizes 4 percent of original principal a year, so the debt is sized to retire inside the contract term and the residual is not load-bearing in the lender’s base case. Equity keeps it, and equity is not being paid separately for it.
Three residuals and the substitution error
Residual value is doing too much work as a phrase, so separate it into the three things people actually mean.
Equipment residual is what the G3520K itself fetches on resale. Site residual is what the lateral, the permits, the land and the interconnection are worth to a different user. Contract residual is the revenue that remains after the original compute tenant is repriced or leaves.
Sort the evidence by which one it speaks to, and the picture changes. The bull case is almost entirely an argument about equipment residual, and it’s a decent one. Graham is evidence about site residual, specifically interconnection residual. NVIDIA’s Ohio guaranty protects the site and lease residual. Nobody has produced evidence of contract residual beyond a single renewal data point.
The bear case is that behind-the-meter models treat these three as substitutes. They aren’t. A portable engine can hold value on a site that doesn’t. A valuable site can hold value after its original engines are worthless. And a bespoke gas lateral with no grid interconnection is not interchangeable with Graham’s ERCOT position, which is the specific scarcity that made Graham trade.
The bull case, which is better than it usually gets credit for
The strongest argument against all of this is liquidity, and it’s a real one.
Reciprocating engines are modular, containerized and factory-standard. Caterpillar’s backlog has grown more than 3.5 times since early 2024. New large recip orders are landing in late 2027 at the earliest and mostly 2028, per Evercore ISI’s David Raso. INNIO’s largest order in company history is 2.3 GW with VoltaGrid across 92 prime-rated 25 MW packs. In a market that tight, a genset whose tenant walks has somewhere to go, and the site-level evidence supports it: Stream paid Plug Power up to US$76.5 million for 66 acres and 164 MW of ERCOT interconnection at Graham, Texas, roughly US$466 per kW for a hydrogen plant that was never built. Power certainty has repeatedly survived the total obsolescence of whatever was built on top of it.
Two things cut against the extrapolation.
First, Graham traded as an interconnection position. Nobody bought an operating fleet; they bought a grid position that was expensive to replicate. A behind-the-meter site with no interconnection and a bespoke gas lateral has no equivalent scarcity to sell.
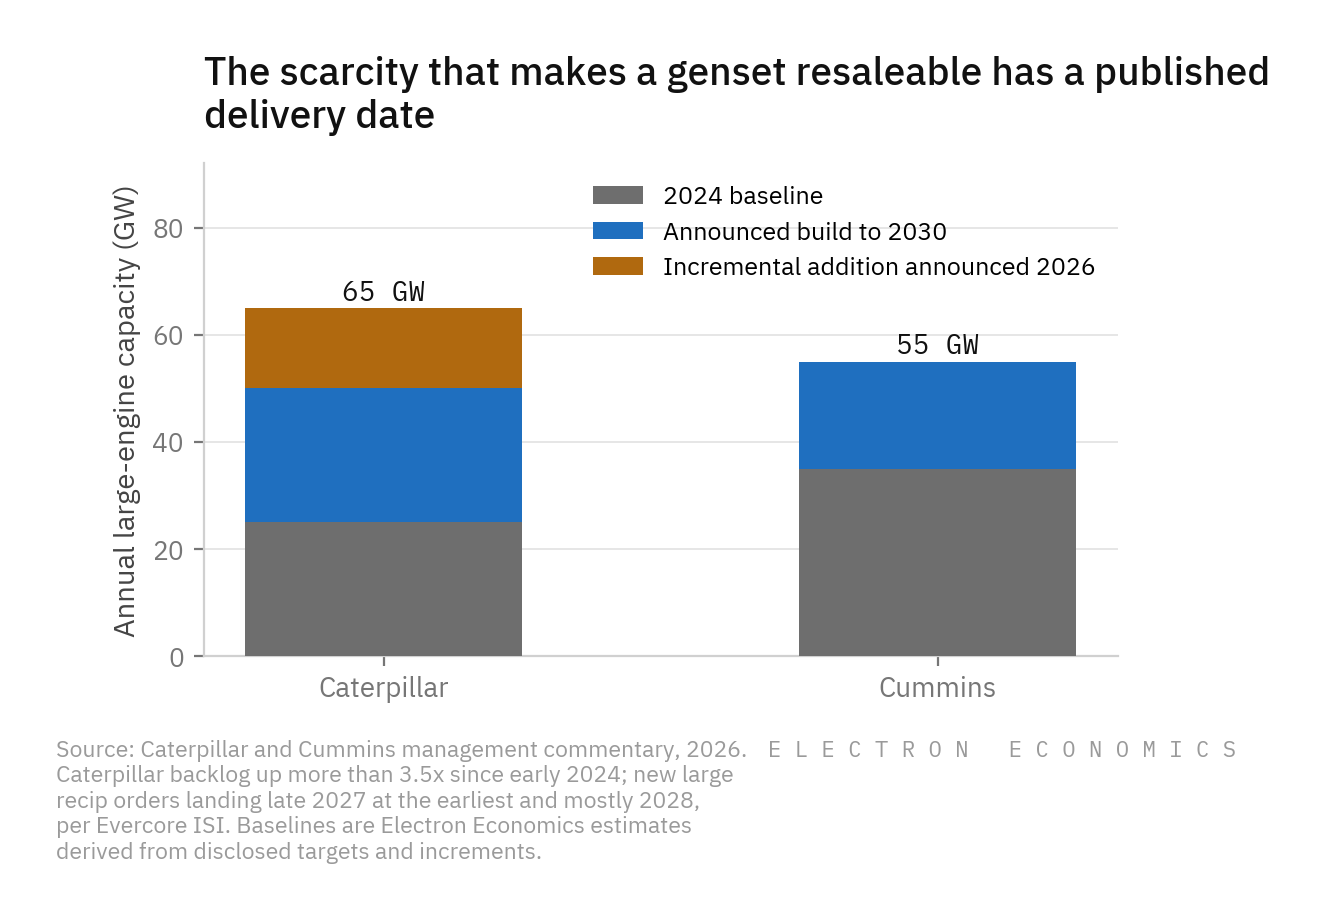
Fig 8 — Caterpillar and Cummins between them are adding 35 GW a year of large-engine nameplate. Sources in the figure.
Second, the tightness that makes engines liquid is being manufactured away on a schedule. Caterpillar is adding 15 GW of annual large-engine capacity on top of the 50 GW it had targeted by 2030, against a 2024 baseline near 25 GW. Cummins is adding 20 GW to reach 55 GW. That capacity build is a direct threat to the scarcity premium embedded in today’s used-engine residual assumptions. Once buyers can obtain new equipment within normal lead times, there is no obvious reason a used fleet should continue to clear at near-replacement economics. The scarcity is the asset. The scarcity has a delivery date.
Joule’s own site sells the pitch as “Speed to Market, No waiting on Public Utilities.” The engines land in early 2028, which is roughly what an interconnection queue was quoting before anyone decided to call it slow.
Who wears the residual under the concrete
Work down the stack and name the party.
The hyperscaler holds the renewal decision and almost nothing else. It exits at lease end into a market where somebody else has already sunk the lateral.
Nvidia holds a defined slice, and less of it than the headline. US$6.3 billion in capacity purchases; US$105 billion at PORTS-Pike, phased in from fiscal 2029, declining as OpenAI pays rent and is reimbursable; US$3.5 billion in land, power and shell guarantees; a platform participation still without a published ceiling. Note what the US$105 billion bought: a retail PPA and a commitment to a transmission upgrade. Nvidia underwrote the grid.
The neocloud holds duration, utilization and now the covenant package. CoreWeave’s July term loan marketed at SOFR plus 425 to 450 and closed at SOFR plus 550 at 97, an all-in 10.44 percent, with a 1.35 times debt service coverage test, US$112.5 million of minimum liquidity and full amortization. That’s what unguaranteed exposure in this chain costs today.
The power developer holds the residual under everything, unhedged. A 20-plus year fleet, a permanent lateral, an unpriced islanding election, curtailment conditions that in Texas run with the asset and reopen inside five years, and a lease that runs 10 to 15 years against hardware upstairs on a six-year book.
The stress case doesn’t require a crash. It requires renewals to converge toward spot instead of holding near the 95 percent of prior pricing CoreWeave reports on rebooked H100 capacity. If the compute contract reprices at renewal, the lease reprices behind it, and the developer is holding a 12-year-old engine fleet on a site whose gas lateral serves one customer who no longer needs it. Nobody upstream is contractually obliged to care.
I’ve sat on the buy side of enough of these to know which line the investment committee actually fights about, and it’s never the depreciation footnote. It’s the terminal value in year 11. In these models that number is doing an enormous amount of work and nobody has bought insurance on it.
If I had to bet my own dollars: I’d rather own the interconnection position and the gas lateral than the gensets sitting on them, and I’d want the lease term to reach at least 15 years before I financed a fleet at 2028 delivery prices. Buy the scarcity that can’t be manufactured. The engines can be, and Caterpillar and Cummins have published the schedule on which they will be.
The behind-the-meter gas thesis does not fail if AI demand disappears. It fails if the terminal value assumed in year 11 was actually a scarcity premium earned in years 1 through 5.
Nvidia has now shown what it will insure across that horizon: the customer relationship, land, shell, retail power procurement and the wires required to deliver it. No disclosed instrument reaches the generating plant.
So don’t ask whether the engines work. Ask what the engines are worth in year 11, after Caterpillar has built another 15 GW a year of manufacturing capacity, the first GPU fleet has been depreciated twice over, and the customer owns the renewal decision.
That is the residual nobody upstream has bought.
Electron Economics maintains five live research tools: BTM Gas Gen Deployment, Deals Intelligence, Capex Intelligence, Forecast Model and the Large Load Tariff Tracker.